
Best Investments for Children's Future in India: 7 Smart Plans
Planning for your child's future is one of the most important financial goals you will ever have. Education costs are rising fast. You want to make sure the money is there when your child needs it. This guide explains the best investments for children's future in simple words.
You will learn about safe government schemes like SSY and PPF. You will also see post office plans and LIC policies. No complicated jargon. Just clear information to help you choose wisely. Read this guide start early, Invest regularly,give your child a secure future.
Start with a Clear Goal
Before you pick any investment, ask one question. What is the money for? Higher education? Marriage? A first business? Each goal has a different timeline.
If the goal is 10 or more years away, you can take some equity risk for growth. If it is 5 to 10 years away, blend equity with safe options. If it is under 5 years, keep the money safe and easy to reach .
Education inflation is real. A course that costs 10 lakh today could cost about 26 lakh in 10 years and 42 lakh in 15 years, assuming 10% annual inflation . Plan for that number, not today's cost.
Read More: Best Investment Plan for Child Future: Secure Tomorrow with Smart Planning
Best Investments for Children's Future in India
1. Sukanya Samriddhi Yojana (SSY) – Best for a Girl Child
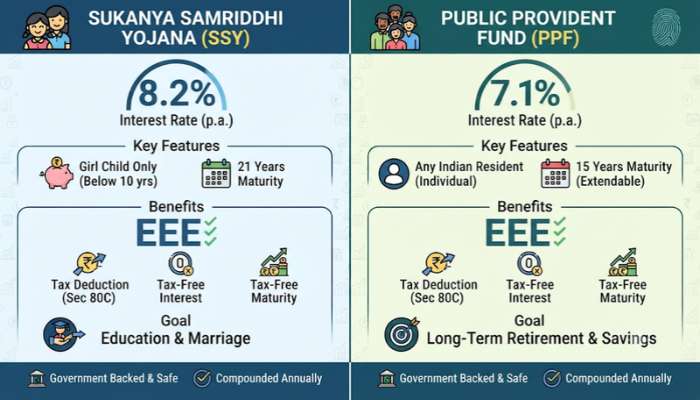
SSY is a government-backed scheme designed for a girl child. It currently offers 8.2% interest, the highest among small savings schemes . The interest is fully tax-free.
You can open an account before the girl turns 10. The minimum deposit is 250 per year. The maximum is 1.5 lakh per year. The account matures 21 years from opening, but you only need to contribute for 15 years .
The tax benefit is EEE status. Your investment qualifies for Section 80C deduction (old regime). The interest is tax-free. The maturity amount is also tax-free . This makes SSY a powerful long-term wealth builder for a daughter's education or marriage.
2. Public Provident Fund (PPF) – Best for Safety and Tax-Free Returns
PPF is open to any Indian resident. You can open an account in your minor child's name. The current interest rate is 7.1% . Like SSY, it has EEE tax status. Investment, interest, and maturity are all tax-free .
The lock-in is 15 years. The maximum deposit is 1.5 lakh per year. You can extend it in blocks of 5 years . PPF is not the highest-return option. But it is one of the safest. It works well as the stable foundation of your child's portfolio.
3. Equity Mutual Funds via SIP – Best for Long-Term Growth
If your goal is 10+ years away, equity mutual funds have historically beaten education inflation. A Systematic Investment Plan (SIP) lets you invest a fixed amount every month. You can start with 500 .
A 15-year SIP of 3,000 per month in an aggressive hybrid fund could grow to about 14.43 lakh, assuming 12.12% annual returns. This is roughly 5 lakh more than what PPF delivers over the same period . But returns are not guaranteed. Markets can fall in any given year.
The trade-off is liquidity. Mutual funds are easy to withdraw. This can be a problem if you lack discipline. Experts suggest pairing a locked instrument like PPF or SSY with an equity fund. The lock-in keeps the goal money safe from temptation, while the fund adds growth .
4. Best Investment Plan for Child in Post Office
The post office offers several schemes for children. Here is a quick comparison.
- Sukanya Samriddhi Yojana is available at post offices. It offers 8.2% tax-free interest for a girl child .
- National Savings Certificate (NSC) offers 7.7% over a 5-year lock-in. You can open it for a minor. For the first four years, the interest is reinvested and qualifies for 80C deduction. Only the fifth year's interest is taxable .
- Post Office Time Deposit for 5 years qualifies for 80C. But the interest is taxed every year at your slab rate. TDS may apply .
- Kisan Vikas Patra (KVP) doubles your money in about 9.5 years at 7.5%. But there is no 80C benefit, and the interest is taxable .
For a child's future, SSY (for girls) and NSC are the better post office options. They offer tax benefits and safe returns.
5. Best One-Time Investment Plan for Child
If you have a lump sum to invest, you have options.
- Single Premium Child ULIP combines market-linked growth with life insurance. You pay once, and the money grows over time. The life cover protects your child if something happens to you . But ULIPs have charges, and returns depend on market performance. Compare costs carefully.
- Sukanya Samriddhi Yojana is also a strong one-time option for a girl child. You can deposit up to 1.5 lakh per year. Starting early gives the money more time to compound .
- PPF works for a one-time deposit too. You can put in up to 1.5 lakh in a year and let it grow tax-free for 15 years.
For a pure one-time investment with no insurance component, a diversified equity fund or an aggressive hybrid fund may give the highest long-term returns. But you must be comfortable with market risk.
Best Investment Plan for Child LIC
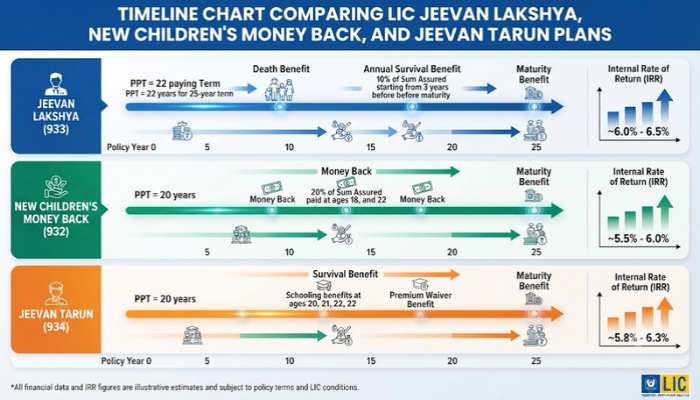
LIC offers traditional child plans that combine savings and life insurance. Here are the top three based on Internal Rate of Return (IRR) .
- Jeevan Lakshya (Plan 933) has the highest IRR at 7.02%. It pays 10% of sum assured every year from year 2 to the end of the policy term. At maturity (age 25), you get the full sum assured plus bonuses. If the parent dies, the premium is waived, and the child still gets the benefits .
- New Children's Money Back (Plan 932) has an IRR of 6.87%. It pays 20% of sum assured at ages 18, 20, and 22. The remaining 40% plus bonuses comes at maturity (age 25). This is good if you want cash flows during college years .
- Jeevan Tarun (Plan 934) has an IRR of 6.86%. It offers flexible money-back options. You can choose to receive 0%, 5%, 10%, or 15% of sum assured each year from age 20 to 24. The rest comes at maturity (age 25) .
These LIC plans are safe and come with a premium waiver rider. But the returns are modest compared to equity funds. They work best for parents who want guaranteed returns and life cover in one product.
You May Also Read: Cybersecurity Stocks Investment Trends: Top Indian and Global Stocks to Watch in 2026
Quick Summary Table
FAQs
1. What is the best investment for a child's future in India?
It depends on the goal and timeline. For a girl child, SSY is excellent with 8.2% tax-free returns. For long-term growth (10+ years), equity SIPs have the highest potential. For safety, PPF is reliable. Many experts suggest combining a locked scheme like SSY or PPF with an equity fund .
2. What is the best post office scheme for a child?
Sukanya Samriddhi Yojana is the best for a girl child. It offers 8.2% tax-free interest. For a boy, NSC is a good option with 7.7% returns and partial 80C benefit. PPF is also available at post offices and offers 7.1% tax-free .
3. What is the best one-time investment plan for a child?
For a girl child, SSY is a strong one-time option up to 1.5 lakh per year. For market-linked growth with insurance, a single premium child ULIP works. For pure growth, a lump sum in a diversified equity fund can give the highest long-term returns, but with market risk .
4. Which LIC plan is best for a child?
LIC Jeevan Lakshya has the highest IRR at around 7.02%. It pays annual survival benefits and a lump sum at maturity. New Children's Money Back is good if you want payouts at ages 18, 20, and 22. Jeevan Tarun offers flexible payout options .
5. How much should I invest monthly for my child's future?
Use a goal-based approach. Estimate the future cost of education (assuming 10% inflation). Then work backwards to find the monthly SIP needed. Starting early reduces the monthly amount required. Even 3,000 per month for 15 years can build a significant corpus .
6. Is SSY better than PPF for a child?
SSY offers a higher interest rate (8.2% vs 7.1%) and is designed specifically for a girl child. But it is only available for daughters. PPF is available for any child. Both have EEE tax status and similar lock-in periods .
7. Can I open a PPF account for my son?
Yes. A parent or guardian can open a PPF account in a minor's name. The account can be converted to the child's name once they turn 18. The same 7.1% tax-free interest applies .
8. Should I buy term insurance for my child's future?
Term insurance is for the earning parent, not the child. If the earning parent dies, a term plan pays a sum assured that keeps the child's goals on track. Experts recommend buying term cover on the parent's life and keeping insurance separate from investments .